Quick Overview
- What does collision insurance cover? Depending on the plan you choose, it primarily covers accidents, theft, vandalism, and damage caused by natural disasters.
- Is it mandatory? No. By law, third-party liability insurance—commonly known as “compulsory liability insurance”—is mandatory.
- When is collision insurance worth it? Primarily for newer or higher-value cars, and especially if you would have difficulty covering the cost of repairs or the loss of the vehicle yourself.
- What should you watch out for? Exclusions, deductibles, the insured value of the vehicle, how the insurance payout is calculated, and the scope of roadside assistance services.
Did the insurance company deny or reduce your claim? Before accepting their decision, have your insurance policy, the terms and conditions, and the way the insurance company assessed the damage reviewed. We can help you.
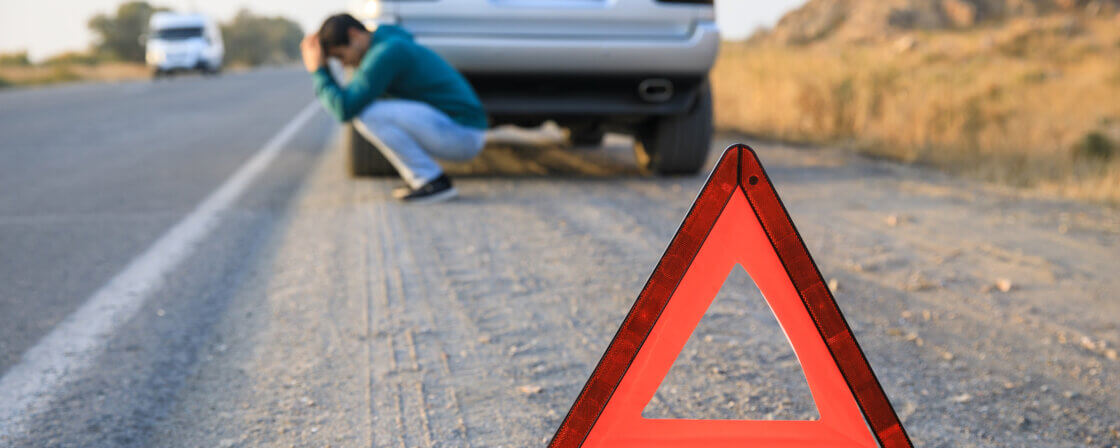
Imagine you park your car in front of a store, go shopping, and when you return, you find that someone has backed into it. And of course, they drove off! Or you come to your car in the morning and are horrified to see that the windows are smashed, the tires are gone, and a brick is lying next to it. What now? That’s when comprehensive auto insurance comes into play—a policy that will save not only your wallet but also your peace of mind.
What’s the difference between comprehensive insurance and liability insurance?
Every driver must have car insurance—specifically, liability insurance—which covers damages if you cause an accident involving someone else. It acts as a sort of protective shield for other road users. Sure, but what about your car? If someone hits you and flees the scene, liability insurance won’t help you. That’s where comprehensive auto insurance comes in—it protects your vehicle directly.
Comprehensive insurance is a voluntary form of insurance that protects your car against various risks, such as accidents, theft, or vandalism. Unlike liability insurance, which only covers damage you cause to other road users, comprehensive insurance protects you and your property directly.
The Act on Motor Vehicle Liability Insurance stipulates the obligation to have compulsory liability insurance. Comprehensive insurance, however, is not mandatory, although in some cases it becomes a condition of the contract—this is the case, for example, with leased vehicles.
Simply put:
- Third-party liability insurance —covers damage you cause to someone else.
- Comprehensive auto insurance —covers damage you sustain.
If you want peace of mind and don’t want to worry about who damaged your car, comprehensive auto insurance is the right choice.
Are you solving a similar problem?
Do you need legal advice?
Our online legal advice service is here to answer your questions about any legal issue. Whether you’re having trouble with auto insurance or don’t know where to file for divorce, just write to us and you’ll receive a response within 48 hours.
I have a question
- When you order, you know what you will get and how much it will cost.
- We handle everything online or in person at one of our 6 offices.
- We handle 8 out of 10 requests within 2 working days.
- We have specialists for every field of law.
What Does Collision Insurance Cover?
What comprehensive auto insurance covers depends primarily on the plan you choose. Typically, it can protect your car in the event of an accident, theft, vandalism, or damage caused by natural disasters. However, the scope of coverage varies among insurance companies, so the specific terms and conditions always apply.
There are various types of collision insurance based on the scope of coverage:
- Collision Insurance: Covers damage to your own vehicle in the event of an accident.
- Theft Insurance: Protects you in the event of theft of the vehicle or its parts.
- Vandalism Insurance: Covers damage caused by intentional acts (e.g., scratching the paint with a key).
- Natural disaster insurance: Covers damage caused by hail, floods, or a falling tree.
So, for example, imagine you return from a full day of skiing to your parked car and discover that an avalanche of snow has fallen from the roof onto your hood. Do you have car insurance? Then you’re in the clear. Without it, you’d have to shell out a hefty sum for repairs and possibly even a tow.
What doesn’t comprehensive car insurance cover?
But even comprehensive car insurance isn’t unlimited. Even in this case, there are situations where the insurance company won’t pay out on this policy. These include, for example, damage caused by negligence ( such as driving under the influence of alcohol). Comprehensive insurance also doesn’t cover normal wear and tear on the vehicle, nor does it cover damage to the interior caused by negligence. Yes, spilling coffee on a seat and damaging the upholstery isn’t grounds for an insurance payout. Also, keep in mind that you really won’t be compensated, for example, for setting your own car on fire or causing other intentional damage. Insurance companies also do not cover damage caused intentionally.
Tip from legal practice:
In disputes with insurance companies, the issue is often not just whether the damage actually occurred, but also how precisely the insurance terms and conditions are worded. Terms such as “usual repair costs,” “comparable replacement part,” or specific exclusions can have a significant impact on the amount of the insurance payout. Therefore, if a claim is denied or significantly reduced, we recommend focusing not only on the amount in question but also on the exact wording of the insurance policy and the General Insurance Conditions.
How much does collision insurance cost?
Comprehensive insurance premiums vary depending on several factors. The first is the age and value of the vehicle. Newer and more expensive cars naturally have higher premiums. A luxury SUV will have a more expensive policy than a standard small hatchback.
Another factor is where you plan to park your car. Cars garaged in a single-family home have lower premiums than those parked in a residential complex, as they are generally better protected against theft, vandalism, and adverse weather conditions.
Deductibles also come into play. The higher the deductible you choose—that is, the amount you pay out of pocket in the event of a claim—the lower your premium will be.
Finally, insurance companies also take your driving history into account. If their records show that you’ve hit a deer, rear-ended the car in front of you at a traffic light, or backed into a street sign, insurers will view you as a higher-risk client, so your car insurance will cost you more.
How to Choose the Right Car Insurance Policy?
When choosing comprehensive insurance, pay close attention to what the policy actually covers. Some people need to protect their car from hail, while others face a higher risk of theft. In any case, make sure the insurance covers all the situations you need protection for. Also, consider the deductible. The higher you set it, the lower your premium will be. However, you must take into account that in the event of a claim, you’ll pay a larger amount out of your own pocket. It’s up to each individual to decide which risk seems more acceptable. Also focus on the roadside assistance services offered. Good collision insurance should provide towing in the event of an accident, on-site repairs, and ideally a loaner car until yours is repaired.
Various comparison websites can help you make your choice; some insurance companies offer better assistance, while others have higher coverage limits.
When Is Comprehensive Car Insurance Worth It?
Car insurance isn’t something you can generalize about. Everyone has to decide for themselves whether they want car insurance. If you have an older car worth 50,000 crowns, comprehensive insurance probably isn’t worth it for you. Repairs for such a car often cost less than several years’ worth of insurance premiums. But if you drive a new car or a leased vehicle, then auto insurance is definitely a smart investment.
It’s especially worth considering comprehensive insurance if:
- you have a new or higher-value car,
- you’re financing the car with a loan or lease,
- you don’t have sufficient financial reserves for major repairs or vehicle replacement,
- you frequently park in areas with a higher risk of vandalism or damage,
- you also want to protect yourself against natural disasters, theft, or an accident caused by your own fault.
So it’s not just about the car’s age. The decisive factors are the ratio of its value to the insurance premium, the deductible amount, and the amount you would be able to pay out of pocket in the event of a claim.
Comprehensive Insurance in Practice: A Dispute Over Repair Costs
The importance of the precise wording of insurance terms and conditions is also illustrated by a dispute heard by the District Court for Prague 8 in 2025. When settling a collision claim, the insurance company calculated the insurance payout so low that, after deducting the deductible, it effectively paid the client nothing.
Among other things, the court addressed the question of what “parts of comparable quality” meant under the insurance policy terms. In the case of this specific luxury vehicle, taking into account its characteristics and the expert’s conclusions, the court determined that new original parts were necessary for a proper repair. It therefore ordered the insurance company to pay the remaining portion of the insurance benefit.
This case demonstrates that in a dispute over collision insurance, the mere occurrence of the damage may not be the only decisive factor. The interpretation of the insurance terms and conditions, the method of calculating repair costs, or the expert assessment can also be crucial. However, each case must be evaluated based on the specific contract and circumstances.
The insurance company does not necessarily have the final say. If it has denied your collision claim or, in your opinion, unjustifiably reduced the payout, we will review the insurance policy and the company’s arguments and suggest the next steps.
Summary
Collision insurance is a voluntary type of insurance that, depending on the agreed-upon coverage, protects your own vehicle in the event of, for example, an accident, theft, vandalism, or damage caused by natural disasters. Whether collision insurance is worth it depends primarily on the value of the car, the premium, the deductible, and how much damage you can afford to pay out of pocket. It therefore generally makes the most sense for newer and more valuable vehicles. When taking out a policy, pay attention not only to the price but, above all, to the scope of coverage, exclusions, the deductible, how the insurance payout is determined, and roadside assistance services. If the insurance company refuses to pay or significantly reduces the payout, the exact wording of the contract and the insurance terms and conditions may be decisive.
Frequently Asked Questions
Do I need to have collision insurance for a leased car?
Comprehensive auto insurance is not required by law. However, a leasing or lending company may require it as a condition of the vehicle financing agreement.
Can I get collision insurance for an older car?
Yes. However, the insurance company may take into account the car’s age, value, and condition. For a very inexpensive car, it’s a good idea to compare the premium with the maximum possible loss.
Does collision insurance cover collisions with wildlife?
It can, but it depends on the specific scope of the insurance coverage. A collision with wildlife may be covered under comprehensive insurance or as a separate rider.
Does collision insurance cover a cracked windshield?
According to the insurance policy, glass damage may be covered under comprehensive insurance; however, a separate glass coverage rider is often purchased.