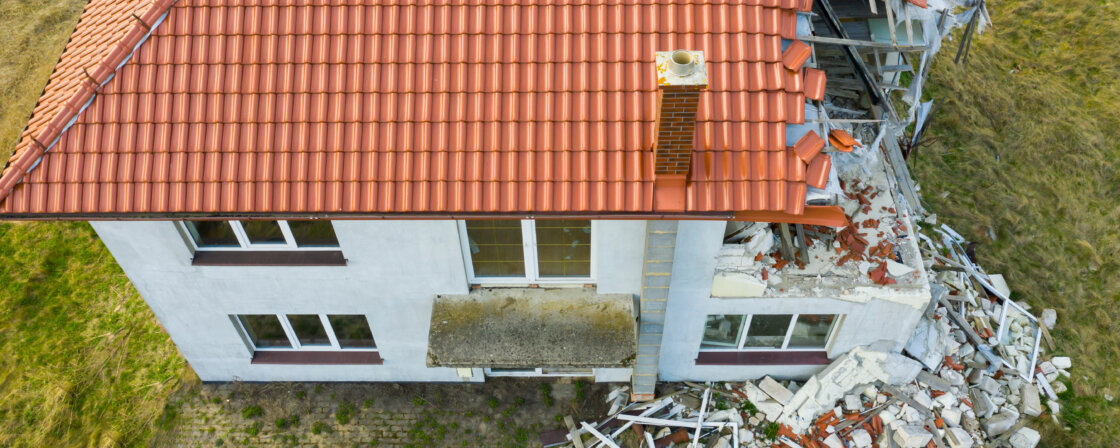
Insurance is recommended for all property owners. It provides them with financial protection against damage caused by natural disasters, fires, vandalism, or other unexpected events. Property insurance is particularly important in areas with a higher risk of flooding or other natural disasters.
Whether you’re purchasing insurance for a house or an apartment, it’s always important to choose the right type and scope of coverage that matches the property’s value and the owner’s individual needs. It’s also important to consider the location, the property’s condition, and the risks it may face. Be sure to carefully review the policy terms and conditions, particularly any exclusions and limitations. If you’re unsure whether your insurance policy provides sufficient protection, we’d be happy to help you with a legal review of it. We’ll alert you to potential risks and advise you on how to proceed if a dispute arises with the insurance company or if it refuses to pay out your claim.
When is property insurance required, and when is it merely voluntary protection of your assets? Property insurance is typically a requirement when obtaining a mortgage, as the bank requires it to protect against damage to or destruction of the mortgaged property. However, this is not a general legal obligation. The specific insurance requirements are set forth by the bank in the loan agreement.
The obligation to obtain property insurance may thus arise from the loan agreement, not from a general legal obligation of the property owner.
Are you solving a similar problem?
Are you unsure whether your insurance policy actually protects your property?
Please contact us. We will review the terms and conditions, point out any potential legal risks, and help you find a suitable solution.
I'd like some advice
- When you order, you know what you will get and how much it will cost.
- We handle everything online or in person at one of our 6 offices.
- We handle 8 out of 10 requests within 2 working days.
- We have specialists for every field of law.
Property Insurance for a Mortgage
Property insurance for a mortgage primarily serves to protect both the bank and the property owner. By arranging this insurance, the bank protects its investment, because in the event of damage to or destruction of the property, the loss can be covered by the insurance payout. Property insurance for a mortgage therefore protects both the borrower and the lender.
As a rule, the insurance must be purchased and proof of coverage provided no later than before the mortgage funds are disbursed, with the specific deadline set by the bank. The insurance must then be maintained for the period required by the loan agreement, typically for the entire term of the mortgage.
The cost of mortgage property insurance depends on the property’s value and the scope of coverage. It is not necessarily more expensive than standard property insurance, but it must meet the bank’s minimum coverage requirements. Insurance is crucial for protecting both the property owner and the bank in the event of unforeseeable events, such as natural disasters or fires. The bank typically defines the scope of coverage that the policy must include, and in addition, you can purchase coverage for other areas that are important to you.
Tip for article
Are you interested in learning how to buy an apartment with a mortgage? Then don’t miss our next article, where you’ll learn about the requirements for getting a mortgage.
What does property insurance cover?
Property insurance generally covers the building itself and its permanent fixtures, such as the roof, windows, floors, and utility lines. However, it does not cover household contents, such as furniture, electronics, or personal belongings. These must be covered by a separate home contents insurance policy.
It’s also true that while you must comply with the bank’s requirements specified in the loan agreement for building insurance, you have greater flexibility with home contents insurance and can tailor it to your needs.
When purchasing a property financed by a mortgage, a situation may arise where you need to take out insurance even before your ownership is registered in the real estate registry. In this case, insuring someone else’s property is possible because you have a legitimate insurable interest.
If you wish to make significant changes to the insurance policy or take out a policy with another insurer, you must take into account the terms agreed upon with the bank. The bank may have arranged for the insurance proceeds to be restricted in its favor or for other forms of security.
Tip for article
The cost of property insurance is determined based on a number of factors that reflect the risks associated with a specific property. Which of these factors are fixed, and when can you influence the cost of your policy yourself? We explore these questions in our next article.
Home Construction Insurance
When is home insurance essential, even during construction? Primarily when the construction is financed by a mortgage and the bank requires insurance coverage. However, even in other cases, insurance for a house under construction is highly recommended. It protects the owner’s investment against unforeseeable events, such as fires, floods, or theft of building materials, provided these risks are included in the agreed-upon coverage.
But how do you insure something where one week you’ll find piles of bricks, and in the following weeks, for example, steel frames and profiles—and where the entire structure is constantly changing? Moreover, it may not even be possible to secure it adequately for a certain period of time.
Home construction insurance typically covers damage caused by unforeseeable events such as fires, floods, theft, or vandalism. It is important to regularly update the insured amount so that it corresponds to the actual value of the investment. Insurance companies often offer flexible solutions that allow you to adjust your coverage on an ongoing basis according to the current status and value of the construction project. Some insurance companies also offer special packages for home construction insurance that can later be easily converted to standard property insurance.
What is property owner’s liability insurance?
Property liability insurance protects property owners from financial claims by third parties for damages caused in connection with the property. This includes, for example, injuries on the property’s grounds or damage caused by objects falling from the property. If someone suffers damage and claims that the condition of your property is to blame, this insurance can protect you from financial claims and legal disputes.
Tenant Property Insurance
There is one significant—and, moreover, very common—situation in which it is advisable to insure a property you do not own: tenant-held property insurance. In this case, however, it typically involves contents insurance—that is, coverage for the items the tenant has brought into the property. These include furniture, books, jewelry, electronics, and other personal belongings. Tenant property insurance is highly recommended because, in most cases, the property owner’s home or apartment insurance does not cover the tenant’s personal property or damage caused by the tenant. The apartment owner cannot even know what property is currently in the apartment. However, it is advisable to clarify when signing the lease agreement which party is insuring the apartment, what is being insured, and to what specific extent.
Tenant Property Insurance
In our law practice, we encountered the case of Mr. Pavel, who lived in a rented apartment. The landlord assured him that the apartment was insured and that he didn’t need to worry about anything. However, when thieves broke into the apartment and stole a computer and other electronics worth 170,000 CZK, a problem arose.
Mr. Pavel expected the insurance company to cover his losses. It turned out, however, that the landlord’s policy only covered damage to the apartment—specifically, broken glass—and not the tenant’s stolen belongings.
Cases like this show how important it is to distinguish between property insurance and household insurance. If your insurance company refuses to pay compensation, you should review your insurance policy, the circumstances of the damage, and any other potential legal claims. We’d be happy to help you with this and assess whether there’s a way to seek compensation for the damage through other means.
Tip for article
Have you signed a lease and aren’t sure exactly what rights and obligations it entails? We’ll advise you on whether you’re allowed to have a pet in your apartment or have guests over if the lease prohibits it.
How might insurance for a room or building that hasn’t received a final inspection differ?
Insurance companies may view properties that have not been approved as a higher risk due to potential safety or structural deficiencies. As a result, the coverage offered may be limited, or specific insurance conditions may be required. It is important to discuss these aspects with the insurance company and clearly specify the nature of the uninspected room when purchasing insurance.
Tip for article
Do you want to switch insurance companies because of unsatisfactory terms? Or have you found a much better offer? Read on to find out when you can terminate your insurance policy.
Summary
Property insurance protects owners from the financial consequences of fire, flooding, vandalism, and other unexpected events. It is not required by law, but banks typically require it when you take out a mortgage. You can also insure a house under construction or, under certain conditions, someone else’s property. Renters should primarily consider home contents insurance and liability insurance.
When choosing a policy, it is essential to set the insured amount correctly and to review the scope of coverage and any exclusions. Insufficient coverage can result in significantly lower insurance payouts. If you are unsure about the terms of the policy or are dealing with a dispute with the insurance company, it’s worth consulting an expert.
Frequently Asked Questions
Is property insurance required by law?
No. However, the bank usually requires insurance when granting a mortgage.
What is the difference between property insurance and home insurance?
Property insurance covers the building and its permanent fixtures. Home contents insurance protects your belongings, such as furniture, electronics, and personal items.
Can a house that is under construction or has not yet been approved for occupancy be insured?
Yes. However, insurance companies may impose special conditions, limit the scope of coverage, or require additional security measures for the building.
What does it mean when insurance proceeds are restricted for a mortgage?
A restriction on disposal protects the bank’s interests by limiting how the insurance proceeds may be used for its benefit. The specific method of disbursing the funds in the event of a claim depends on the agreed-upon terms.