Quick Overview
What types of property insurance are available?
Types of property insurance can be distinguished based on the insured structure as well as the risks covered by the policy. For example, you can insure a single-family home, an apartment, a vacation home, or a garage. For each option, however, the key factor is what the property is actually protected against. The following overview distinguishes between individual types of coverage and related insurance policies; these are not standardized product names used by all insurance companies.
| Coverage or Related Insurance |
What it’s for |
What to check |
| Natural disaster insurance for real estate |
Covers agreed-upon damages, such as those caused by fire, windstorms, or hailstorms. |
Which natural disasters the policy covers and how they are defined. |
| Flood and inundation coverage |
Protects against specified types of property flooding. |
Whether both risks are included, what their limits are, and any applicable waiting period. |
| Coverage for Water Damage |
Covers, for example, damage caused by water leaks from pipes. |
Does it also cover the search for the source of the leak and the repair of the damaged pipe? |
| Theft and vandalism coverage |
It can protect building components against theft or intentional damage. |
Security requirements and conditions for filing a claim. |
| Coverage for glass and technology |
This may include, for example, broken glass, power surges, or damage to selected equipment. |
Whether specific devices are covered and against which causes of damage. |
| Homeowners Insurance |
Protects furnishings and other personal property. |
Which items and spaces are covered, and what are the specific coverage limits. |
| Liability Insurance |
Covers the obligation to compensate for harm caused to others. |
Whether it covers liability arising from ownership or rental of real estate. |
Jednotlivá krytí mohou být součástí jednoho balíčku nebo se sjednávat zvlášť. Rozhoduje konkrétní smlouva a pojistné podmínky, nikoli pouze název produktu.
Not sure how to interpret an exclusion or limitation in your insurance policy? At our legal advice center, we’ll help you assess the rights and obligations arising from a specific provision.
Property Insurance vs. Home Contents Insurance
We most commonly encounter property (structure)insurance, which covers damage to the building itself, whether it’s a single-family home, a cottage, a garage, or even an apartment. It protects against, for example, floods, fires, vandalism, or various natural disasters. Of course, this protection doesn’t mean that a flood or fire can’t happen, but if it does and the house burns to the ground, you’ll be reimbursed for a significant portion of the resulting damage.
The second most common type of property insurance is home contents insurance. This, however, protects the personal belongings inside an apartment or house. Typically, this includes furniture, electronics, and personal items. This insurance covers damage resulting from, for example, theft or property damage.
Liability insurance for damage caused to third parties is often included with these types of policies.
When choosing insurance, it is important to consider the value of the property and its contents, the risks associated with its location (e.g., flood-prone areas), and the owner’s specific needs. Insurance companies offer various packages and add-ons, such as coverage against natural disasters or liability insurance for damages caused while renting out the property.
Choosing the right insurance ensures peace of mind and protects your investment. However, it’s not enough to simply choose an insurance company, take out a policy, and just pay the premiums for years and decades to come. You also need to regularly review and update your policies to ensure they reflect current values and needs.
Property Natural Disaster Insurance: What Does It Cover?
Natural disaster property insurance may cover, for example, fire, lightning strikes, explosions, windstorms, or hailstorms. The specific list varies depending on the product and the selected scope of coverage. Therefore, you cannot assume from the term “natural disaster” alone that the policy also covers floods and flash floods.
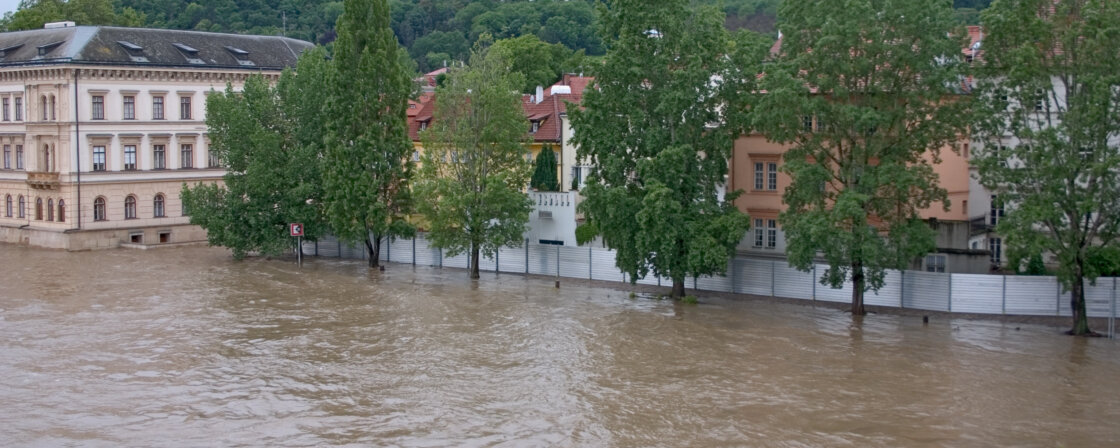
Check coverage for water damage separately. A burst pipe is a different cause of damage than water from an overflowing river or torrential rain. When comparing quotes, be sure to look for specific risks, their definitions, and coverage limits.
Are you solving a similar problem?
Are you buying or selling a property?
We provide comprehensive legal services related to the purchase or sale of real estate, including a reservation agreement and escrow of the purchase price. We can also assist with the land registry and taxes. We’ll handle everything quickly and flawlessly so you don’t have to worry about a thing. You can pay after the service has been provided.
I'd like some advice
- When you order, you know what you will get and how much it will cost.
- We handle everything online or in person at one of our 6 offices.
- We handle 8 out of 10 requests within 2 working days.
- We have specialists for every field of law.
I’m Taking Out an Insurance Policy—What Should I Watch Out For?
When taking out an insurance policy, it’s important to pay attention to several key aspects. First , read the entire policy thoroughly , including all the fine print. That’s where exclusions are usually hidden, and they can change the situation. It’s essential to understand exactly what is covered and what falls under the exclusions. You may assume that your apartment is fully protected (at least financially) against fire, but an exception listed on page nine of the policy terms and conditions specifies situations where the insurance company will not pay you anything because the fire was caused by your electric kettle, your minor child, or storage heaters that do not meet the latest technical specifications. It is also important to verify that the insurance coverage limit corresponds to the value of your property and belongings.
The deductible defines your financial responsibility in the event of a loss, so it’s important to pay special attention to it. Find out how and within what timeframe you must report a claim to the insurance company. Be sure to inquire about any additional fees and the terms for automatic policy renewal.
Review the options and rules for making changes to the insurance policy. Finally, do not overlook the insurer’s reputation and financial stability, which are a guarantee of its reliability and ability to fulfill its obligations in the event of a claim. Carefully selecting an insurance policy and an insurance company can save you a lot of trouble in the future. When insuring real estate, it’s also worth checking other customers’ experiences with real estate insurance.
What can I insure?
When it comes to real estate, you can insure a wide range of property. In addition to the house itself, you can also insure greenhouses, wells, land, gardens, sheds, various outbuildings, and other property accessories. However, it’s a good idea to think of everything and specify it in the policy so you aren’t unpleasantly surprised in the event of a claim. It’s important to consult with your insurance company about coverage options to ensure your property is fully protected.
Tip for article
Property insurance can be recommended at any time and under any circumstances. Such a statement would be enough to wrap up this topic. However, in our article, we’ve focused on specific situations, such as insuring someone else’s property, insuring an apartment when taking out a mortgage, and insuring a house that’s still under construction.
What should I do in the event of an insured incident?
When an insured event occurs (such as a fire, flood, or windstorm), the top priority is, of course, to ensure everyone’s safety and minimize further damage. Document the extent of the damage in as much detail as possible; this will make it easier to communicate with your insurance company. Take photos of everything and make a list of what has been destroyed or lost.
Contact the insurance company as soon as possible to report and accurately describe the damage. At this stage, it is crucial to follow all of the insurance company’s instructions, especially regarding repairs and the claims settlement process. Do not make any repairs until the insurance company approves them. It is also important to keep all documents related to the damage for the potential processing of the insurance claim. Following the correct procedure can speed up the claims process and minimize complications.
It is important to follow the insurance company’s instructions and meet all deadlines and requirements for reporting the claim.
Restrictions on Property Insurance Proceeds
In some cases (typically involving a mortgage), a so-called restriction on insurance proceeds or a restriction on property insurance may apply. This is essentially a restriction on the right to dispose of the proceeds, which means that the insurance proceeds or other benefits from the policy will not be paid to the policyholder but to the policyholder’s creditor. Therefore, if a house burns down, the money from the insurance policy will go to the creditor (the creditor could be a bank, for example).
Tip for article
The cost of property insurance is determined based on a number of factors that reflect the risks associated with a specific property. Which of these factors are fixed, and when can you influence the cost of your policy yourself? We explore these questions in our next article.
What Mistakes Should You Avoid When Taking Out an Insurance Policy?
When taking out property insurance, it is essential to carefully review the insurance policy. It is important that you fully understand all the terms and conditions of the coverage, including a thorough understanding of the exclusions.
It’s also important to accurately assess the value of your property. Underestimating the value of your property can lead to underinsurance. In that case, your policy won’t cover the full value of the damage in the event of a claim. Conversely, overvaluing your property leads to overinsurance, which may mean you’re paying higher premiums than necessary.
Underinsurance can have an impact even in the case of minor damage: A house has an insured value of 8 million crowns, but the sum insured is only 4 million. If a covered loss of 600,000 crowns occurs and a proportional reduction is applied due to underinsurance, the payout before deducting the deductible may amount to only 300,000 crowns. This is a simplified example; a specific policy may exclude such a reduction or modify the conditions for its application.
It is also important to regularly update your insurance policy in the event of any changes, such as home renovations or the addition of new property. These changes can affect the value of your property and, consequently, the amount of your insurance coverage.
Finally, be sure to consider all risks associated with your property. Every property is unique and may require specific insurance coverage. Carefully consider all potential risk factors to ensure that your insurance policy adequately addresses all possible scenarios.
Avoiding the mistakes mentioned above can help ensure that your property is properly insured and protected against unexpected events.
Is your insurance company reducing your payout due to underinsurance, and are you unsure how they calculated it? Have your policy, the terms and conditions, and the notice of the compensation amount ready. At our legal advice center, we’ll help you assess whether their actions comply with the agreed-upon terms.
Tip for article
Do you want to switch insurance companies because of unsatisfactory terms? Or have you found a much better offer? Read on to find out when you can terminate your insurance policy.
Summary
Property insurance protects the building and its fixed components, while home contents insurance covers furnishings and other personal property. The scope of coverage is determined by the agreed-upon risks: in addition to natural disaster coverage, be sure to check specifically for flood, inundation, water damage, theft, and vandalism. Before signing, compare exclusions, limits, deductibles, and coverage for outbuildings or equipment. Keep the insured amount up to date, as underinsurance can reduce your compensation even in the event of partial damage. In the event of a claim, ensure safety, prevent further damage, document everything, and report the incident to the insurance company without undue delay. If you have a mortgage, also verify the conditions for payment of the claim in relation to the bank.
Frequently Asked Questions
Does the insurance take effect immediately after signing the contract?
Not necessarily. It depends on the agreed-upon start date of the insurance and any other applicable terms and conditions. For certain risks, such as floods, a waiting period may be specified during which the right to a payout has not yet arisen.
Is a photo enough when reporting a claim if I don't have any receipts?
Photos are important, but they alone may not be enough to prove the value of the damaged item. Please also include any available invoices, warranty cards, payment statements, or other supporting documents. Check with your insurance company for specific requirements.
Do I need to notify my insurance company about the installation of a photovoltaic system or a heat pump?
Review the disclosure requirements in the contract and discuss the change with your insurance company. New technology may increase the value of the property and may also require different coverage than the building itself.
What if the insurance company takes longer than three months to investigate the claim?
They must provide you with a written explanation of why the investigation cannot be concluded. Upon request, they must provide a reasonable advance payment, unless there is a reasonable basis for refusing to do so. Therefore, three months is not an automatic deadline for the payment of the full compensation.
By when must the insurance company pay out the insurance claim?
Unless otherwise agreed, payment is due within 15 days of the conclusion of the investigation. Therefore, the deadline generally does not begin on the date the claim is reported.