Quick Overview
- Before granting a mortgage, the bank assesses your income, expenses, existing debts, and the value of the property being used as collateral.
- Upon sale, the mortgage can be paid off using the proceeds from the sale. The bank must approve the buyer’s assumption of the debt or any change to the collateral.
- For a renovation mortgage, the contract specifies how funds are to be drawn down, how the use of funds is to be documented, and the deadline for completing the work.
- The bank typically requires insurance for the mortgaged property. Homeowners insurance or proof of repayment ability does not substitute for this.
Are you selling a property with a mortgage? We can help you with the legal aspects of the sale, including aligning the purchase agreement, escrow, and loan repayment terms.
Be sure to read the second and third installments of this series as well.
In the second part, you’ll learn about non-bank mortgage options and why they may or may not be worth it. You’ll also find a description of how a mortgage works for a foreclosed property that you purchased at auction. You’ll also find out whether it’s possible to take out a mortgage on commercial real estate and what alternatives might be available. Finally, you can learn how early mortgage repayment works.
The third part focuses on the option of buying a house on an installment plan without a mortgage. You’ll also learn what conditions you must meet to get a mortgage for a plot of land. We’ll also answer questions regarding mortgages for cooperative apartments and the options for mortgages without real estate collateral or with another property as collateral.
How a Mortgage Works: Basic Information
A mortgage is a loan secured by a lien on real estate. With a standard home mortgage, you repay the borrowed principal and interest in regular installments. The fixed-rate period determines how long the agreed-upon interest rate remains the same; it is not the same as the total repayment period.
The property used as collateral does not have to be the same property you are buying or renovating. However, the bank assesses its acceptability and value.
What are the conditions for a mortgage?
The bank primarily verifies your ability to make payments, the value and legal status of the collateral, and the purpose of the loan. Under the Consumer Credit Act, the bank must assess your creditworthiness, specifically your income, expenses, and existing obligations.
In 2026, the general upper limit for the LTV—that is, the loan-to-value ratio—is 80%. For applicants under 36 years of age purchasing their first home, the limit is 90%. There is no entitlement to an exception above the specified limit.
For investment mortgages, the CNB recommends stricter limits effective April 1, 2026: an LTV of no more than 70% and total debt of no more than seven times net annual income. Individual banks may have stricter conditions, and meeting these limits does not in itself guarantee loan approval.
How to Sell a Property with a Mortgage?
There are several situations in which you might need to sell a house or apartment with a mortgage. For example, you may be unable to keep up with your payments, you may be getting divorced and no longer want to make joint payments, or you may have found a new home and want to sell your old one. It’s also common for people to want to sell an apartment with a mortgage and buy a house. So what is the process for selling an apartment, house, or plot of land with a mortgage?
Are you solving a similar problem?
Are you planning to sell or buy a property?
If you are buying or selling real estate, it’s worth taking advantage of escrow services. This way, you can be sure your money is safe. If you’d like to set up an escrow account or need assistance with the process of buying or selling real estate, please contact our attorneys.
I want to help
- When you order, you know what you will get and how much it will cost.
- We handle everything online or in person at one of our 6 offices.
- We handle 8 out of 10 requests within 2 working days.
- We have specialists for every field of law.
Early Mortgage Repayment When Selling a Property
The first option for resolving this situation is to pay off the mortgage early. You can do this either with your own savings or by taking out a new loan to pay off the mortgage. This way, you’ll be selling the property free of a mortgage. However, this method is not always available to everyone.
If you’re having trouble making your mortgage payments, one option is to refinance. You can apply for refinancing as soon as your fixed-rate period ends. If refinancing does not result in lower monthly payments and total interest, you can try transferring your mortgage to another bank where you may be able to get more favorable terms.
Selling a Property with a Mortgage
Another option is to sell the property along with the mortgage. The main obstacle to this approach, however, is that you must find a buyer who is willing to purchase the property along with the mortgage, and the buyer must also be approved by the bank that holds your mortgage. If the bank does not approve the buyer, there is still the option of refinancing the mortgage and transferring it to another bank that will approve the buyer.
Another option is to find a buyer who has sufficient funds of their own to purchase the property and pay off your mortgage outright. Alternatively, they can take out a mortgage to pay off your mortgage. However, this may present a problem in the form of penalties for early repayment of the mortgage. These penalties apply only if you have a fixed-rate mortgage; once the fixed-rate period ends, they no longer apply.
Transfer Your Mortgage to Another Property
Last but not least, there is also the option of transferring your mortgage to another property, though this is a fairly complex and time-consuming process. In practice, this involves transferring the mortgage from your current property to a new one. This allows you to sell your current property free of the mortgage.
The main criterion for transferring a mortgage to a new property is that your new property (i.e., the property that the bank will now hold as collateral) must have a sufficiently high value. If it does not have sufficient value, you can provide another property as collateral (e.g., your parents’ apartment).
Tip for article
Read about how to buy an apartment with a mortgage.
If you decide to transfer your mortgage to another property, you’ll go through the same process as you did with your original property. This means you’ll need to obtain an appraisal of your new property, file an application to register the mortgage in the land registry, and insure the property. The bad news is that these services come at a cost, and you may also have to pay bank fees for transferring the mortgage. The entire process is also quite time-consuming due to the involvement of the land registry office.
Can I take out a mortgage to renovate a house?
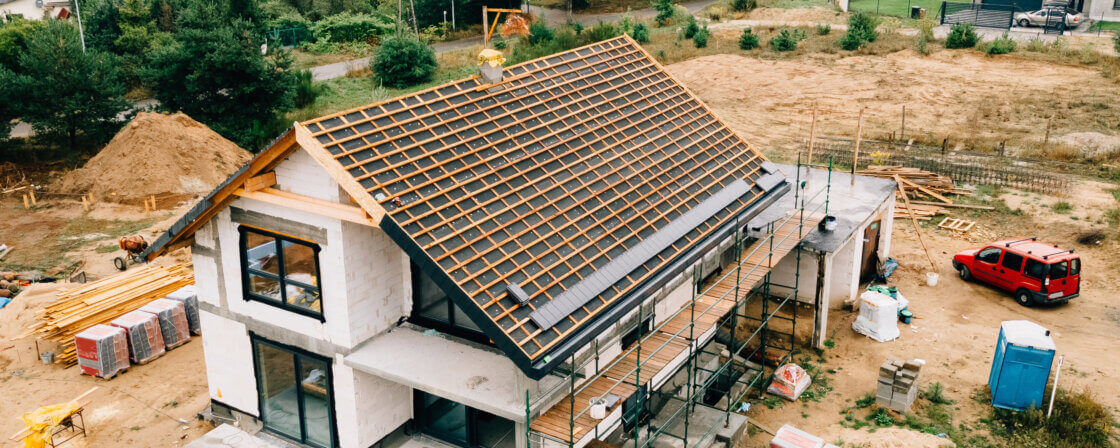
Have you inherited an older house from your parents, or does your current home—or the one you’re planning to buy—need extensive repairs, but you don’t have the savings needed for the renovation? Don’t worry—there’s a mortgage specifically for home renovations.
A renovation mortgage isn’t much different from a traditional real estate mortgage. With a home renovation mortgage, you also use real estate as collateral —either the property you plan to renovate or another property (e.g., if the value of the property being renovated isn’t sufficient). However, what sets a home renovation mortgage apart is how the funds are disbursed. Specifically, there are two methods:
- Drawing the entire amount at once based on an expert’s estimate—for this, you’ll often need to have an itemized budget and a construction schedule ready.
- Drawing down the amount in installments, with invoices submitted as proof of work completed.
You’ll certainly also be interested in how budget increases and construction delays work in the case of a renovation mortgage, where the price is clearly set. You don’t need to worry that this will cause you any problems. In fact, this is a common occurrence that’s taken into account. You can draw down a higher amount than estimated, and likewise, you can usually draw down a lower amount if the renovation ends up costing less. In addition, a renovation mortgage usually includes a non-purpose portion. You can use the money from this portion for anything (e.g., buying a pool, furniture, or electronics).
Tip for article
If you’re planning to renovate your home, don’t miss out on the “Renovate Your Grandmother’s House” grant program. Through this program, you can receive grants for insulation, solar panels, replacing your heating system, water heating, or an electric vehicle charging station—up to 50% of eligible expenses.
Do I need to insure my property when I take out a mortgage?
Simply put, yes. Property insurance is a requirement for obtaining a mortgage. It covers damage to the structure and structural components of the property (such as radiators or solar panels). The bank requires property insurance because it protects the bank from potential loss. While you’re paying off the mortgage, the bank holds your home as collateral, and if something were to happen to it, the bank would lose part or all of the collateral’s value. In the event of damage, the insurance company pays the insurance proceeds to the bank, which then transfers them to you. You must then use those funds to repair the damage.
How to Choose Property Insurance
In most cases, the bank itself determines yourproperty insurance; however, if you’re arranging property insurance on your own, these tips will come in handy:
- Clarify your needs: Determine the type and value of your property, and identify potential risks and vulnerabilities specific to its location and type (for example, if your home is located in a flood zone, it’s worth insuring against that risk).
- Do your research: Carefully research what the insurance market has to offer. The main factor determining the quality of your insurance is the coverage amount—that is, what the insurance company will pay you in the event of a loss. Also, make sure the policy covers all potential claims that might affect you.
- Set a budget for your insurance premiums: Consider how much you can afford to invest in property insurance,
- Take advantage of discounts and packages: Ask about discounts for bundling multiple insurance policies (e.g., auto and home insurance).
- Seek expert advice: Consider consulting with an insurance agent or broker who can provide personalized advice.
Tip for article
Do you need help choosing insurance, financing a property, or with any other issue related to your finances? Then contact our partner, Corona Lecta. They’ll discuss your financial, asset, and life goals with you and propose a well-thought-out strategic plan for achieving them.
When you’re considering whether to take out a mortgage for a house or an apartment, don’t forget that you need to thoroughly research everything first. Careful planning, financial foresight, and a thorough understanding of the available options will enable you to navigate the complex real estate market and secure the best possible solution.
Summary
A mortgage can finance both the purchase and renovation of a property; however, the bank always assesses the borrower’s ability to repay and the value of the collateral. Upon sale, the original loan can be paid off using the sale proceeds, or—with the bank’s consent—the debt can be assumed or the collateral changed. Early repayment costs depend on legal requirements and the terms of the specific loan agreement. For renovations, you must verify in advance how funds will be drawn down, document the purpose of the funds, and understand the procedure for budget changes. The bank typically requires insurance for the property being renovated, but you may choose your own insurance company as long as you meet the required coverage.
Be sure to read the second and third installments of this series as well.
In the second part, you’ll learn about non-bank mortgage options and why they may or may not be worth it. You’ll also find a description of how a mortgage works for a foreclosed property that you purchased at auction. You’ll also find out whether it’s possible to take out a mortgage on commercial real estate and what alternatives might be available. Finally, you can learn how early mortgage repayment works.
The third part focuses on the option of buying a house on an installment plan without a mortgage. You’ll also learn what conditions you must meet to get a mortgage for a plot of land. We’ll also answer questions regarding mortgages for cooperative apartments and the options for mortgages without real estate collateral or with another property as collateral.
More Frequently Asked Questions About Mortgages
Is an approved mortgage the same as being able to withdraw the money immediately?
No. Before drawing down the loan, you must meet the terms of the loan agreement, such as providing the required documents, proof of insurance, or confirmation that the lien has been properly registered.
What if the bank appraises the property at a value lower than the purchase price?
When calculating the LTV, the bank bases its calculation on the value of the collateral it recognizes. A lower appraisal may therefore mean that you’ll need to contribute more of your own funds or provide additional acceptable real estate as collateral.
Does paying off a mortgage automatically result in the removal of the lien from the land registry?
No. As a general rule, the lien is extinguished upon repayment of the secured debt; however, its removal from the land registry requires the appropriate document and the filing of a petition for removal.
Can I do the renovation myself?
For some mortgages, yes. Check in advance how the bank will verify the purpose of the loan and the work process, and which expenses it will cover.
Can I have property insurance from a different company than my loan repayment insurance?
Yes. These are different types of insurance. For property insurance, you must meet the bank’s requirements regarding the scope of coverage and provide proof of the policy.