Is someone seeking damages from you, or has an insurance company refused to pay your claim? Our attorneys will review your situation, your insurance policy, and the validity of the claim, and will help you assert your rights.
What is liability insurance?
Simply put, it’s insurance that covers damage caused to a third party. So if you unintentionally cause harm to someone else’s health, property, or finances, the insurance company will cover that damage for you. Of course, this is subject to the agreed-upon terms and conditions. The policy may also include a deductible—that is, the amount you’ll have to pay out of pocket in the event of a claim. However, some insurance companies also offer policies without an deductible. When choosing a policy, therefore, always check how high the deductible is for your policy and what the maximum coverage limit is.
There are typically two basic types of liability insurance. The first is liability insurance for everyday civil life, which covers daily activities outside of work or business. The second type is employee liability insurance, which covers damages caused while on the job. We will now focus on personal liability—that is, situations that can easily happen to any of us.
What the Civil Code Says About Liability for Damages
Liability insurance has its legal basis in the Civil Code. The law distinguishes several types of liability that you can insure against. These include:
- Liability for one’s own actions
- Liability for children
- Liability for an animal
- Liability for property or conditions (e.g., snow falling from a roof)
The basic principle is simple: If you cause damage to another person by breaching your legal obligation, you must compensate them for that damage. And it is precisely against this risk that you can purchase insurance, so that the insurance company will cover the damage on your behalf if necessary.
Are you solving a similar problem?
Do you need legal advice?
We’ll provide it to you within 48 hours, without you having to go anywhere. Just fill out our online form and send us your inquiry.
I'm going to ask
- When you order, you know what you will get and how much it will cost.
- We handle everything online or in person at one of our 6 offices.
- We handle 8 out of 10 requests within 2 working days.
- We have specialists for every field of law.
What Does Liability Insurance Cover, and When Is It Worth It?
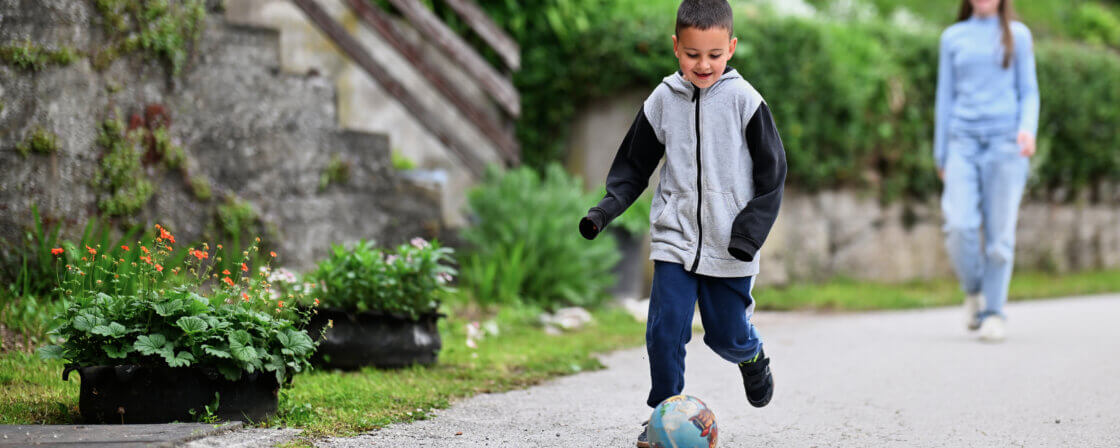
Liability insurance for damage in everyday life covers damage caused unintentionally by you, your child, a pet, or an object during normal activities. Typical examples include situations where your child is playing with a ball and breaks a neighbor’s window, or when you’re visiting friends and knock over a glass of red wine onto their new, expensive sofa. Or when your dog breaks free from its leash, runs into the street, and causes a traffic accident. You’ll also appreciate liability insurance when you collide with another skier on the slopes while on vacation.
In these cases, the insurance covers compensation for damages to the injured party (whether an individual or a legal entity), as well as any legal representation costs if you’re unable to reach a mutual agreement and your dispute goes to court.
A major advantage of liability insurance is that it often extends beyond just you. With many insurance companies, it also covers other members of your household, such as a spouse, partner, or children. Some policies even cover children who live away from home while attending school. The insurance may also cover damage caused by your pet. However, before taking out a policy, always verify exactly who is insured and whether the policy covers all members of your household.
The scope of coverage typically ranges in the millions of crowns, and the coverage limit generally has a significant impact on the premium amount.
Broken Items at a Neighbor’s House: Who Pays for the Damage?
All it takes is a moment of inattention, and while visiting your neighbors, you might knock over an expensive vase, break a TV, or damage furniture. Damage caused to a neighbor—who actually pays for it? Generally speaking, the person legally liable for the damage must compensate for it. So, for example, if you accidentally knock over your neighbor’s TV due to your own carelessness, your neighbor can demand compensation from you for the resulting damage.
The situation becomes more complicated if a child causes the damage. Parents are not automatically liable for it. It depends on the child’s age, their abilities, and whether someone failed to fulfill their duty of supervision.
What if you have liability insurance? In that case, the insurance company may pay the compensation if you are legally liable for the damage and the incident falls within the agreed-upon coverage. However, this does not mean that your neighbor will automatically receive enough money to buy a brand-new TV. The amount of compensation is determined based on the actual damage, taking into account the value of the item before it was damaged and the reasonable costs of repairing it.
So, if you break something at your neighbor’s house, document the damage and contact the insurance company as soon as possible. This will help you avoid a situation where you accept an unreasonably high claim without first having it assessed.
If the circumstances of a case or the norms of private life so require, everyone is obligated to act in such a way as to avoid causing unjustified harm to the liberty, life, health, or property of another.
In what cases will the insurance company not cover your claim?
Not all damages are automatically covered. Insurance companies typically list exclusions in their policy terms and conditions, which you should read carefully before signing the contract. The most common exclusions include:
- Damage caused intentionally
- Damage caused under the influence of alcohol or drugs
- Damage to borrowed or rented items
- Damage between members of the same household
- Professional activities (these are already covered by professional liability insurance)
We also strongly recommend verifying whether your liability insurance policy is valid outside the Czech Republic. Because if you travel abroad (for example, to go skiing in Austria), causing damage (such as injuring another skier) can significantly complicate the entire situation if you do not have adequate insurance coverage. However, most modern liability insurance policies are now valid throughout the European Union, and some even worldwide.
Specific situations where liability insurance can save you
Spilled wine on an expensive rug at a friend’s house
While visiting friends, one moment you might be enjoying the party, and the next you’re dealing with the fact that you accidentally dropped a glass of red wine on a light-colored wool rug that your friends brought back from a vacation in Morocco. But the stain won’t come out, and the rug is ruined, so your friends are demanding compensation of 30,000 CZK. In this case, liability insurance covers the cost of the damage. After you report the incident and provide the necessary invoices, the insurance company will reimburse the damage, saving you a significant amount of money and preserving your good relationships.
A visiting child breaks a TV
Your 10-year-old child is visiting a classmate. While playing with a ball, he hits an LCD TV, which breaks. The parents demand compensation of 18,000 CZK. Thanks to liability insurance, the damage is covered—the insurance company pays the full amount to the affected party. If you didn’t have insurance, you’d have to pay the compensation out of your own pocket.
A Dog Causes a Traffic Accident
While walking your dog, your pet breaks free from its leash and runs into the street. A driver, trying to avoid a collision, swerves and damages his car. The cost of repairing the car and towing it amounts to nearly 70,000 CZK. Since you have liability insurance for everyday life, the insurance company will cover the entire damage for you. This type of policy also covers damage caused by pets.
Tip for article
Spilled coffee on a laptop or a crashed company car? These are just some of the situations where employee liability insurance can help you. You can read more about it in our article.
Cyclist on Roller Skates Struck by a Car
You fail to brake in time on a bike path and hit a passing cyclist. The cyclist has a broken collarbone and a damaged bike. Medical treatment and bike repairs cost more than 100,000 CZK. If you didn’t have liability insurance, you’d have to pay for everything yourself. Since you’re covered, the insurance company will cover the costs for you.
Damage to a Neighbor’s Car While Moving
While moving furniture, you accidentally bump the corner of a wardrobe into your neighbor’s parked car, causing a dent in the door. The repair costs 12,000 CZK. If you have liability insurance for everyday life, the insurance company will cover the damage, and you’ll avoid a dispute with your neighbor.
An Unfortunate Collision on a Ski Slope in the Alps
During a winter vacation in Austria, you accidentally collide with another skier on the slope, breaking their leg. The costs of treatment, hospitalization, and lost wages will amount to several thousand euros. Since your personal liability insurance is valid abroad as well, the insurance company will cover all costs. Without insurance, you would face not only financial expenses but also the possibility of criminal charges.
So what is the purpose of liability insurance? Above all, it protects you from having to pay unexpected damages out of your own savings. Even a seemingly minor accident can lead to high costs, especially if it results in injury to a person or damage to expensive property.
An Example from Our Law Practice
For example, we handled a case involving a client who, through an unfortunate accident, flooded her neighbors’ apartment while living in a rental unit. The water damaged the floor and some of the furnishings in their apartment, and the neighbors demanded compensation of nearly 90,000 CZK. The client had liability insurance, but the insurance company refused to pay, citing an exclusion regarding rented property.
After reviewing the insurance policy, we determined that this exclusion applied to property rented to the client, not to the neighbors’ property. We therefore prepared legally substantiated objections to the denial of the insurance claim and demonstrated why the damage fell within the agreed-upon coverage.
The insurance company subsequently reconsidered its original decision and recognized the claim for compensation for the proven damage. As a result, the client did not have to pay the entire amount out of her own pocket.
Similar disputes show that a mere rejection by the insurance company does not necessarily mean you are not entitled to an insurance payout. The correct interpretation of the contract and legal argumentation are decisive.
What to Do in the Event of a Loss?
If a situation arises that may be covered by insurance, act immediately. First and foremost , document the damage, take photographs, and secure any witnesses. Also, contact your insurance company as soon as possible. Next, fill out the claim form and submit the necessary documents, such as invoices, estimates, medical records, or photographs.
The insurance company will then assess the circumstances of the incident and decide whether to pay a claim and, if so, the amount. It’s also important not to agree in advance with the injured party on a specific amount of compensation without consulting the insurance company. You could end up acknowledging a claim that is not covered by the insurance at all or that is higher than the actual damage.
Summary
Liability insurance for damage in everyday life provides important protection against the financial consequences of unexpected events. It can help you, for example, in the event of flooding at a neighbor’s home, damage to someone else’s property, an injury sustained while playing sports, or damage caused by your pet. Depending on the policy terms, it may also cover other household members or incidents that occur abroad. When purchasing a policy, it is important to pay close attention to the coverage limit, the deductible amount, the geographic scope, and any exclusions.
However, keep in mind that liability insurance does not automatically cover every type of damage. First, there must be a legal obligation to compensate for the damage, and the specific incident must fall within the scope of the agreed-upon coverage. If damage occurs, document it thoroughly, notify the insurance company promptly, and do not acknowledge disputed claims without prior consultation. If the insurance company refuses to pay or someone demands unreasonable compensation from you, a legal assessment can help you avoid unnecessary expenses and a protracted dispute.
Frequently Asked Questions
What Does Liability Insurance Cover?
It covers legitimate claims for compensation for harm you cause to others—whether to their health, property, or finances—within the scope of the agreed-upon contract.
Is liability insurance mandatory?
Liability insurance for everyday life is voluntary.
Does the "stupid things" insurance also cover damage caused by children?
Yes, if the insurance policy covers that type of liability. It also depends on whether there is a legal obligation to compensate for the damage.
Does liability insurance cover damage caused by a dog?
Generally, yes, provided that the policy covers liability for pets and the damage is not excluded from coverage.
Will the insurance company cover the cost of a broken rental phone?
Not always. Damage to rented items is usually excluded from standard coverage and may require supplemental insurance.
Does liability insurance also cover incidents abroad?
It depends on the geographic coverage of the insurance policy. Some policies cover damage in Europe, while others cover damage worldwide.
What if the insurance company refuses to pay compensation?
Request a written explanation, compare it with the insurance terms and conditions, and file a substantiated objection. If that does not succeed, consider seeking legal assistance.